Thursday, April 21, 2011

NFC Mobile Weekly News April 21st

NFC Payments Appear Too Slow for the Real World 

PCWorld - Keir Thomas - ‎Apr 18, 2011‎
Oracle's research indicates how many bugs there are yet to work out before NFC payments become mainstream. Despite Google's push for us to take up NFC, it would be a huge shame if NFC were rolled-out too early and was rejected by consumers as not ...

North America will be the top NFC market in five years 

InternetRetailer.com - Kevin Woodward - ‎2 hours ago‎
NFC is a wireless technology that enables devices to exchange information—including encryptedpayment card data—over a short distance.

Patent hints supersonic sounds and magnetic signatures for e-wallet iPhones 

9 to 5 Mac - ‎30 minutes ago‎
I imagine this change could be picked up by a payment terminal (or an iPhone) in sufficient proximity, thereby authorizing a wireless payment transaction. Apple has thus far filed dozens of patent applications related to NFC, which is an acronym fo ...

Annual Mobile Payment Transactions to Reach 45 Billion in 2015; In-Stat 

TMC Net - Rajani Baburajan - ‎1 hour ago‎
The year 2011 is expected to be the year for Near Field Communication (NFC). NFC will evolve from a concept to a strategy.
Mobile Money News Weekly - Week of April 18, 2011 SYS-CON Media (press release) (blog)

NFC East links: Roseman set for draft 

ESPN (blog) - ‎4 hours ago‎
The Eagles are following the lead of the Giants in allowing season-ticket holders the chance to defer the second half of their ticket payment until the league announces there will be a season in 2011. The Washington Post's Mike Jones on some of the ...

Like this story? Share it 

StorefrontBacktalk - Evan Schuman - ‎11 hours ago‎
Some quick context: For years, advocates of NFC (and RFID contactless payment before that) mobilepayments have argued that it will be much faster than magstripe.

These Two Banks Are Snoozing While This Disruptive Technology Surges Forward 

Wall Street Daily (blog) - ‎3 hours ago‎
It's joined forces with mobile payment platform, Payfone, which is capable of integrating NFCtechnology. So I can't rag on American Express today.

Increased NFC adoption to boost mobile payments 

BCS - ‎Apr 20, 2011‎
The increased adoption of near field communications (NFC) by smartphone providers is likely to boost opportunities for the expansion of mobile payment. That is according to market analyst Juniper Research, which said the technology will allow for ...

Angry Birds to Use NFC Technology on Nokia Phones 

Mobiledia - Kendra Srivastava - ‎Apr 20, 2011‎
This interaction uses near-field communications, or NFC, the same technology used by many upcoming mobile payment systems, and which is poised to handle $1.3 trillion in transactions by 2014.

NXP and Poken deliver NFC integrated products for social networking 

EE Herald - ‎6 hours ago‎
The new platform adds to Poken's product portfolio by adding NFC-based loyalty, payment, and access control capabilities to an already-successful range of social media products.

Sprint working on NFC payment for 2011 

IntoMobile - ‎Apr 4, 2011‎
Sprint is already working on an NFC payment system for 2011 and this will enable users to use their phones to “tap to pay.

Apple selling Square mobile payments reader--NFC plans in doubt

Fiercemobilecontent - Jason Ankeny - ‎Apr 18, 2011‎
Industry onlookers have expected Apple to roll out NFC services since mid-2010, when the company named Benjamin Vigier Product Manager of its mobile commerce unit.

Nexus S NFC payment system due later in 2011 with Citigroup and MasterCard? 

Android Community - Chris Davies - ‎Mar 28, 2011‎
Google would apparently not take a cut of the transaction fees, instead only getting a foot in the door on better quality analytics.

Salt Lake City to Give NFC Payment System a Go 

E-Commerce Times - Erika Morphy - ‎Apr 7, 2011‎
Isis formed in mid-November 2010 with the goal of bringing NFC-enabled mobile commerce to Salt Lake City. The program has been billed as being able to serve the city's entire retail community and now, its transit system.

Research and Markets: 2011 Contactless Near Field Communication (NFC) Mobile ... 

TMC Net - ‎Apr 18, 2011‎
Despite this activity, mobile contactless/NFC is a payment option that is battling limited availability of contactless-ready merchant terminals and mobile technology, as well as low consumer demand.
NFC news in brief • 18 April 2011 Near Field Communications World

Sharp growth predicted for m-commerce and NFC by 2014 

Shopsafe - Katie Neilson - ‎Apr 19, 2011‎
NFC is only just making its way into high end smartphones, with the Google Nexus S being the first UK handset to offer integrated compatibility with terminals that allow for contactless payment and other interactive services. Network providers O2 and ...

Amazon May Deploy their Own NFC Payment Service 

Phandroid.com - Kevin Krause - ‎Apr 1, 2011‎
... to Google with the launch of their Appstore for Android followed shortly by the opening of their Cloud Player personal music streaming service, the company is reportedly exploring the possibility of launching their own NFC payment service.

USA Technologies Hails Megatouch Cashless Payment Processing Pact 

Vending Times - Tim Sanford - ‎4 hours ago‎
USA Technologies provides solutions that can accept every form of cashlesspayment, from traditional "swipe" credit and debit cards to prepaid media, contactless smartcards and wireless/cellular phone payment using NFC-enabled instruments.

INSIDE Secure Licenses Advanced ARM SecurCore Technology 

SYS-CON Media (press release) - ‎Apr 20, 2011‎
The ARM SecurCore processor family provides powerful 32-bit secure solutions based upon the ARM architecture and incorporates advanced security features that make SecurCore processors an ideal choice for paymentNFC secure element, pay TV, e-ID, ...

Mopay: Mobile payment interest doubled in North America last year 

VentureBeat - ‎5 hours ago‎
The ability to have companies charge a consumer's phone directly has long been popular in Asia, where phones come equipped with near-field communication (NFC

INSIDE Secure Licenses Advanced ARM SecurCore Technology

ARM Holdings logoImage via Wikipedia

New Partnership Targets INSIDE’s Next Generation of Secure Payments, Digital Security and NFC Solutions

AIX-EN-PROVENCE, France--(BUSINESS WIRE)--INSIDE Secure today announced their intention to provide 32-bit secure processor solutions based on the industry-leading ARM® architecture. Under the terms of a licensing agreement with ARM, INSIDE can now utilize the ARM SecurCore® SC300™ processor for its next generation of secure payments, digital security and NFC solutions.
“We are confident that the combination of the performance, size and power efficiency benefits of our SecurCore technology, with INSIDE’s expertise in secure contactless, contact, embedded and NFC technologies, will result in the development of a broad range of innovative, high-performance secure devices.”
“This new partnership provides continuity with and expands upon the ARM IP license INSIDE inherited when it acquired the Secure Microcontroller Solutions business from Atmel last year,” said Christian Fleutelot, executive vice president, digital security and general manager, VaultIC at INSIDE Secure. “ARM is an important partner for INSIDE, and with this licensing agreement we now have a greater opportunity to apply the latest ARM SecurCore technology wherever appropriate across our entire product portfolio.”
According to Fleutelot, licensing the ARM SecurCore 32-bit processor family IP offers INSIDE easy access to the small die size, energy efficiency, low cost, excellent code density and outstanding performance of the ARM SecurCore 32-bit technology.
“This agreement further underscores the continuing market momentum we have achieved with our 32-bit SecurCore technology as embedded smart card and other technologies migrate to a variety of mobile devices for payment, transit and other secure applications,” said Haydn Povey, director of product marketing, processor division, ARM. “We are confident that the combination of the performance, size and power efficiency benefits of our SecurCore technology, with INSIDE’s expertise in secure contactless, contact, embedded and NFC technologies, will result in the development of a broad range of innovative, high-performance secure devices.”
The ARM SecurCore processor family provides powerful 32-bit secure solutions based upon the ARM architecture and incorporates advanced security features that make SecurCore processors an ideal choice for payment, NFC secure element, pay TV, e-ID, transit, access control and other secure applications.
About INSIDE Secure
INSIDE’s secure semiconductor products power smart cards, mobile devices, acceptance devices and infrastructure systems. The company’s expertise in microcontroller architectures, security, RF/analog design, and vertical market requirements places the company in the forefront of secure contactless, contact, embedded and NFC technologies. INSIDE's innovation, collaboration with customers and commitment to open standards have earned it a leadership position in markets worldwide. INSIDE is headquartered in Aix-en-Provence, France, with offices in Europe, Asia and Silicon Valley. For more information, please visit www.insidesecure.com.
ARM and SecurCore are registered trademarks of ARM Limited. SC100 and SC300 are trademarks of ARM Limited. All other brands or product names are the property of their respective holders. “ARM" is used to represent ARM Holdings plc; its operating company ARM Limited; and the regional subsidiaries ARM Inc.; ARM KK; ARM Korea Limited.; ARM Taiwan Limited; ARM France SAS; ARM Consulting (Shanghai) Co. Ltd.; ARM Belgium Services BVBA; ARM Germany GmbH; ARM Embedded Technologies Pvt. Ltd.; ARM Norway, AS and ARM Sweden AB.
Enhanced by Zemanta

Wednesday, April 20, 2011

Shoppers Squeezed by Spat over Debit Card Use

Licensed to ePaymentNews by the Washington Times:

Consumers are finding themselves squeezed in a heavyweight bout between the nation's big banks and big retailers over the "swipe fees" imposed when shoppers use their debit card at the register. And both sides warn the little guy will suffer if the other side wins...


The Washington Times. Licensed for 1 month on April 20, 2011, for display at http://ePaymentNews.blogspot.com. 


Enhanced by Zemanta

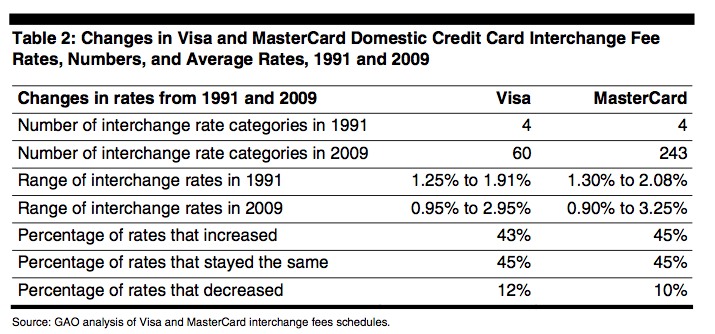
2011 Interchange Rates Rise (Again)

Merchants have been complaining about Interchange Fees for years.  Back in 1991 (simpler times?) there were 4 Interchange rates for Visa and 4 for MasterCard.   Today there are over 300 collectively.  (see illustration below)  Last week, Visa and MasterCard raised the fees yet again...

MasterCard and Visa Raise Interchange Swipe Fees – Again - from Stiel Blog

MasterCard and Visa increased the percentage it takes from merchants and consumers at the point-of-sale, effective April 15th. Merchants have no choice except to pass the higher cost along to every customer in the form of higher prices.

Effective last week (April 15), MasterCard will increase the “base rate” interchange rate for its World Merit III card from 1.73% + $0.10 to 1.77% + $0.10. Merchants actually pay higher fees because the “base rate” is marked-up to merchants based on the type of merchant and their credit card volume. That means many small merchants could pay over 3% to 9%, once all fees are added to the base rates.

Other “base rate” interchange increases disclosed by MasterCard included:

  • World Full UCAF (the rate for a world card e-commerce credit transaction conducted with merchant security and cardholder verification) will increase from 1.83% + $0.10 to 1.87% + $0.10.
  • World Merchant UCAF (the rate for a world card e-commerce credit transaction conducted with merchant security only) increased from 1.73% + $0.10 to 1.77% + $0.10.
  • The Supermarket Base and Enhanced Supermarket Base rates will increase from 1.48% + $0.05 to 1.48% + $0.10.
  • In addition, MasterCard will increase the assessment fee (a flat transaction fee added to the cost of processing each credit card sale) from 0.11 percent to 0.12 percent on consumer and commercial credit volume for transactions of $1,000 or more. 
For a complete list of interchange and fee changes released by MasterCard in April, please go to www.mastercard.com/us/merchant/support/interchange_rates.html .

Visa Inc. also increased fees with its Interregional Super Premium Card with a base rate of 1.97% per transaction. It also added four new Interregional Full Chip Cards with a “base rate” interchange rate of 1.10%. The new cards also add a 0.40% and 0.45% international service and acquirer fees.

Visa and MasterCard increase fees collected from merchants regularly in order to compete among themselves and encourage banks to issue their brand of cards to the hundreds of millions of Americans who pay with plastic. One bank president told us that the “decision over what card to issue is largely based on which one pays us the highest interchange fees.”
Enhanced by Zemanta

Nokia Teams with Proxama for NFC on Nokia C7

From Martin James on the NOK NOK Blog:

Near Field Communication (NFC) technology is big news for Nokia right now, with handsets as far back as the Nokia 6131 NFC having featured the technology on board. However, things have just taken a major step forward with the announcement that Nokia is working with NFC tech specialist Proxama on developing next-gen NFC applications for Nokia smartphones, starting with the Nokia C7.
The Nokia C7 has been earmarked by Proxama to receive a complete NFC-driven service package. This comprises three elements: TagCentre, NFC advertising tags and the PosterTouch campaign manager.
The advertising tags are the sensors that can be programmed with media-rich data and embedded in posters, T-shirts and the like, while the PosterTouch campaign manager allows advertisers and other relevant parties to monitor their NFC campaign’s effectiveness. But for Nokia owners – and Nokia C7 owners in particular – it’s the TagCentre app that’s most important. This piece of software is installed on the phone itself, and decodes raw NFC data into advertisements, movie trailers or whatever else the tag has been set up to link to.
“We are very excited to be at the forefront of the next evolution of the mobile phone,” Nokia’s director of global ecosystems Sixten Sandstrom commented. “At Nokia, we recognise the big impact that NFC is going to have on how people use mobile phones and we plan to fully embrace it.”
Proxama says the first wave of the Nokia-flavoured NFC tech will be focused solely on the Nokia C7, but says its reach will expand over time as NFC starts to take hold and a wider variety of smartphones appear with NFC technology on board.
“Mobile is truly coming of age this year so I am delighted that we have secured a deal that will reap benefits for so many,” Proxama founder and CEO Neil Garner commented.
“We expect take up of NFC activity to grow rapidly with millions of NFC-enabled handsets forecast to be distributed this year. Consumers have increasingly placed more importance on the role their mobile plays in their lives and this is a natural step-change.”

Enhanced by Zemanta

Oberthur Technologies Announces the Availability of its First MasterCard® M/Chip(™) Advance Product

NANTERRE, France--(BUSINESS WIRE)--Oberthur Technologies, a world leader in the field of secure technologies, has announced today the availability of its first MasterCard® M/Chip Advanceproduct.
“Cosmo Fly v4 M/Chip™ Advance will allow issuers to deploy value-added solutions, such as ticketing for transport in open payment fare systems”
Following Oberthur Technologies announcement of the development of MasterCard® M/Chip™ Advance in December 2010, the Cosmo Fly v4M/Chip Advance has been fully certified and is now commercially available for Issuers. The Oberthur Technologies M/Chip Advance card provides issuers with a flexible solution for contact and contactless payments.
In addition to numerous payment-related enhancements, M/Chip Advance also offers Integrated Data Storage capabilities to address the increasing demand for ‘one card’ payment solutions for sectors such as mass transit, loyalty, as well as campus and government entitlement programs.
“Cosmo Fly v4 M/Chip Advance is a major achievement for Oberthur Technologies in its commitment to offer its customers the latest innovations in the industry”, said Cédric Collomb, Cards & Services General Manager, Card Systems Division at Oberthur Technologies. “Cosmo Fly v4 M/Chip Advance will allow issuers to deploy value-added solutions, such as ticketing for transport in open payment fare systems”.
Ed McLaughlin, Chief Emerging Payments Officer at MasterCard Worldwide commented:
“Oberthur Technologies has shown continuous commitment to deliver innovative payment products to our joint Issuing customers. We are delighted that Oberthur Technologies is now ready to deliver M/Chip Advance to MasterCard® Issuers. M/Chip Advance paves the way for future innovation, building on the fast-growing EMV infrastructure worldwide“
About Oberthur Technologies
Oberthur Technologies is a world leader in the field of secure technologies: systems development, solutions and services for smart cards (payment cards, SIM cards, access cards, NFC…) and for secure identity documents, traditional and electronic (identity card, passport, health care card), production of banknotes, cheques and other fiduciary documents, intelligent systems to secure cash-in-transit and ATM. Oberthur Technologies has 6,800 employees through 40 countries and 65 sites. The Group posted 2010 sales of €979M.
Website www.oberthur.com
About MasterCard Worldwide
As a leading global payments company, MasterCard Worldwide prides itself on being at the heart of commerce, helping to make life easier and more efficient for everyone, everywhere. MasterCard serves as a franchisor, processor and advisor to the payments industry, and makes commerce happen by providing a critical economic link among financial institutions, governments, businesses, merchants, and cardholders worldwide. In 2010, $2.7 trillion in gross dollar volume was generated on its products by consumers around the world. Powered by the MasterCard Worldwide Network – the fastest payment processing network in the world – MasterCard processes over 23 billion transactions each year and has the capacity to handle 160 million transactions per hour, with an average network response time of 130 milliseconds and with 99.99 percent reliability. MasterCard advances global commerce through its family of brands, including MasterCard®, Maestro®, and Cirrus®; its suite of core products such as credit, debit, and prepaid; and its innovative platforms and functionalities, such as MasterCard PayPass™ and MasterCard inControl®. MasterCard serves consumers, governments, and businesses in more than 210 countries and territories. For more information, please visit us at www.mastercard.com. Follow us on Twitter: @mastercardnews.

Contacts

OBERTHUR TECHNOLOGIES
PRESS
Corporate:
Charlotte LAFONT-MACHIN
Telephone: +33 1 55 46 71 23
Email: c.lafont-machin@oberthur.com
or
Card Systems Division:
Stéphanie CAU
Telephone: +33 1 47 85 58 06
Email: s.cau@oberthur.com

Enhanced by Zemanta

Report: PCI DSS Compliance Trends Study, 2011

Imperva and The Ponemon Institute have completed a second study on the impact of the Payment Card Industry’s (PCI) Data Security Standards (DSS). The 2011 PCI DSS Compliance Trends Study surveyed 670 US and multinational IT security practitioners on how efforts to comply with PCI-DSS affect an organization’s data protection and security. This report is essential for any organization attempting to comply PCI and wants to benchmark their efforts with their peers.
This year's report shows that:
  • The majority of PCI compliant organizations suffer fewer or no breaches, most practitioners still do not perceive the mandate to have a positive impact on data security.
  • About 64 percent of PCI-DSS compliant organizations reported suffering no data breaches involving credit card data over the past two years, while only 38 percent of non-compliant organizations reported suffering no breaches involving credit card data over the same period.
  • Certain technologies are adopted more quickly than others to comply with PCI. For example, code review saw the biggest decline in adoption.
Redwood Shores, Calif., and Traverse City, Mich., April 19, 2011 -- Imperva, the leader in data security, and the Ponemon Institute announced today the results of their second study on the impact of the Payment Card Industry's (PCI) Data Security Standards (DSS). The 2011 PCI DSS Compliance Trends Study surveyed 670 US and multinational IT security practitioners on how efforts to comply with PCI-DSS affect an organization's data protection and security. This year's report shows that while the majority of PCI compliant organizations suffer fewer or no breaches, most practitioners still do not perceive PCI-DSS to have a positive impact on data security.
Compliant Organizations Suffer Fewer Breaches

According to the study, 64 percent of PCI-DSS compliant organizations reported suffering no data breaches involving credit card data over the past two years, while only 38 percent of non-compliant organizations reported suffering no breaches involving credit card data over the same period. When it comes to overall data breaches (general incident or those involving credit card data), 63 percent of compliant organizations suffered no more than a single data breach, compared to 22 percent of non-compliant organizations. Notably, 26 percent of non-compliant organizations suffered more than five breaches over the same time period.

"At the end of the day, we believe that PCI-DSS is one of the most effective data security regulations today and can significantly help companies improve their data security posture," says Amichai Shulman, co-founder and CTO of Imperva. "Most companies who make an effort to comply with the standards are likely to suffer fewer breaches than those who don't, period."
PCI-DSS Perception is Cynical

Despite evidence to the contrary, the study also found that 88 percent of respondents did not support the claim that PCI-DSS compliance has a positive effect on the number of breaches experienced, and only 39 percent mentioned data security improvement as one of the regulation's value propositions for business. In fact, only 33 percent believe that PCI-DSS compliance expenditure is covered by the value it brings to organization.

"Looking at the figures regarding the actual decrease in data breaches and recent figures regarding the cost of data breaches, it seems that many practitioners have a much subverted perception of the value of PCI-DSS compliance," said Larry Ponemon, chairman and co-founder of the Ponemon Institute.
Nonetheless Compliance Is Increasing

This year's report also found that two-thirds of respondents have achieved substantial compliance with PCI-DSS. In the 2009 PCI DSS Compliance Trends Study, the number of respondents who'd achieved similar levels of compliance was only half, and roughly 25 percent of respondents in 2009 had not achieved any level of compliance. Only 16 percent of organizations surveyed in 2011 have not achieved any level of PCI-DSS by comparison.

"Over the past few years, most companies have matured in their understanding of the PCI mandate and have worked to meet strict compliance deadlines," continued Shulman. "We believe this is one of the primary reasons we've seen an overall increase in compliance and also, we believe, a decline in the number of credit card-related data breaches."

"In an era where governments are struggling with the creation of vague yet complex data protection acts, the credit card industry took a bold step towards regulating itself, using plain language, clear goals and a pragmatic focus," said University of Connecticut School of Business Professor Robert Bird. "PCI isn't perfect - but it succeeded by imposing security mandates and forcing attention on data security - all without government regulation."
For a full version of the 2011 PCI-DSS Compliance Trends Study, visit https://www.imperva.com/lg/lgw.asp?pid=440 .
About Imperva

Imperva is the global leader in data security. With more than 1,300 direct customers and 25,000 cloud customers, Imperva's customers include leading enterprises, government organizations, and managed service providers who rely on Imperva to prevent sensitive data theft from hackers and insiders. The award-winning Imperva SecureSphere is the only solution that delivers full activity monitoring for databases, applications and file systems. For more information, visit www.imperva.com, follow us on Twitter or visit our blog.

About The Ponemon Institute

The Ponemon Institute© is dedicated to advancing responsible information and privacy management practices in business and government. To achieve this objective, the Institute conducts independent research, educates leaders from the private and public sectors and verifies the privacy and data protection practices of organizations in a variety of industries. Visit the Ponemon Institute at www.ponemon.org .


Web Site: http://www.imperva.com/

 . 

Source: Company press release.

First Data to Release Q1 2011 Results on May 4th

First Data to Release First Quarter 2011 Financial Results

ATLANTA--(BUSINESS WIRE)--On Wednesday, May 4, 2011, First Data Corporation will release its first quarter 2011 financial results. The release will be available at http://investor.firstdata.com.
The company will host a conference call and webcast on Wednesday, May 4, 2011, at 10 a.m. EDT to review the first quarter 2011 financial results. Ray Winborne, First Data chief financial officer, will lead the call.
To listen to the call via teleconference, dial 866-804-6923 (U.S.) or 857-350-1669 (outside the U.S.), pass code 33578587. The call will be webcast on the “Investor Relations” section of the First Data website at http://investor.firstdata.com and a slide presentation to accompany the call will also be available on the website.
A replay of the call will be available through May 18, 2011, at 888-286-8010 (U.S.) or 617-801-6888 (outside the U.S.), pass code 85132052, and via webcast at http://investor.firstdata.com.
Around the world, every second of every day, First Data makes payment transactions secure, fast and easy for merchants, financial institutions and their customers. First Data leverages its vast product portfolio and expertise to drive customer revenue and profitability. Whether the choice of payment is by debit or credit card, gift card, check or mobile phone, online or at the checkout counter, First Data takes every opportunity to go beyond the transaction.

Contacts

First Data
Chip Swearngan, 404-890-3000
chip.swearngan@firstdata.com

Disqus for ePayment News