Wednesday, June 22, 2011

NetSecure Launches Kudos, "Square Style Payments to Canada for First time"

NetSecure Technologies Introduces Kudos Credit Card Acceptance Solution in Canada

Kudos Provides a Turnkey “Point of Sale in a Box” Solution for the First Time Ever in Canada, Giving Micro-Businesses a Flexible, Affordable and Secure Way to Accept Credit Card Payments Through a Smartphone, Desktop or Laptop
REGINA, Saskatchewan--(BUSINESS WIRE)--NetSecure Technologies, leading developer of products and security solutions for the eCommerce industry, launched the first mobile payment solution of its kind in Canada – Kudos – a service allowing small business owners to start accepting credit card payments on-the-spot via swipe terminals compatible with desktops, laptops and smartphones (iOS, Android and RIM platforms).
 NetSecure Technologies Ltd.“Up until now, the Canadian market’s mobile payment arena has been virtually non-existent”
Cash-strapped small businesses typically cannot afford payment processing services designed for larger merchants. Canada has approximately 2.5 million micro-businesses that do not accept credit/debit card payments. Costly capital outlays upfront, monthly fees, hidden fees and complex contracts all serve as deterrents.
“Terminals and merchant accounts are expensive,” said Daniel McCann, president and founder of NetSecure Technologies. “The whole process is intimidating to small merchants. Is the musician selling his CD’s after the show really expected to shell out hundreds of dollars for a terminal? We have an opportunity to allow small businesses to accept credit cards using what they already have today – their phones and laptops.”
Mobile payments have proven extremely successful in the United States, dominated by a startup called Square that provides a free service for credit card acceptance, charging users a flat rate for all transactions. This service has already been adopted by hundreds of thousands of small merchants. Unfortunately for Canadians, Square is only available in the United States, leaving a vacuum for credit card acceptance for small businesses in Canada.
“Up until now, the Canadian market’s mobile payment arena has been virtually non-existent,” says McCann. “Through the introduction of Kudos, NetSecure is bringing Square-style payments to Canada for the very first time, making it affordable and convenient for small business owners to start accepting card payments and growing their business.”
The Kudos credit card acceptance kit serves as a complete ‘point of sale in a box’ solution for small business owners. Equipped with a swipe terminal, POS software and a merchant account, users can begin accepting credit card payments through their smartphones or laptops for a flat rate of 2.9 percent per transaction, with no monthly or ongoing fees.
Kudos’ key advantages include no limitations on the amount of transactions and the added benefit of compatibility with RIM platforms, such as Blackberry. Kudos also implements full end-to-end encryption, ensuring security for sensitive data.
“The merchant never needs to see their customers’ credit card numbers, so PCI compliance becomes much easier,” says McCann.
By eliminating lost payments, bounced checks and unnecessary trips to the bank, Kudos helps to improve accounts receivables for small business owners, thereby increasing sales and expanding their customer base.
Kudos is an ideal solution for small business owners and independent professionals, including contractors, consultants, day care providers, repair services, massage therapists, personal trainers, photographers, service employees, tradeshows and events, landscapers, plumbers and more.
“Over half of all transactions today are plastic, and customers are demanding greater flexibility from their vendors,” said McCann. “Smaller businesses that do not offer a credit card payment option are at a competitive disadvantage. NetSecure designed Kudos to take the pain out of payment acceptance for the Canadian business owner and their customers.”
Kudos, available for $49.99 at www.KudosPayments.com, is currently available for free as part of a limited time offer, while supplies last.
For additional information about NetSecure Technologies, visit www.netsecuretechnologies.com and contact Jennifer Reiss at 305-576-1171 X144 or via e-mail at jenniferreiss@maxborgesagency.com.
About NetSecure
Founded in 2005, NetSecure Technologies Ltd. is a technology company focused on developing breakthrough security solutions for online transactions. The company’s products, SmartSwipe and Kudos, are designed to prevent interception of information at the most vulnerable point in the transaction: the point of origin. Integrated with NetSecure’s security patents, the company’s products are unique in the industry, taking the pain out of payment acceptance for businesses of all sizes.

Naratte Introduces Ultrasonic NFC, No Chip Needed

Naratte Delivers NFC Now With a Speaker and a Microphone June 20, 2011 08:00 ET
Zoosh, Powered by Naratte, Utilizes Ultrasonic Technology to Deliver Secure Device-to-Device Communication
SUNNYVALE, CA--(Marketwire - Jun 20, 2011) -
  • Uses the existing speaker and microphone to deliver secure device to device communication
  • With one App update, millions of mobile phones can make secure mobile wallet transactions
  • Uses ultrasonic technology that is inaudible to humans
  • Available now from Naratte with consumer deployments in July
Naratte [rhymes with karate] Inc., a Silicon Valley-based start-up, has announced that it can provide the benefits of near-field communication (NFC) with ultrasonic technology by using the speaker and microphone already found on mobile devices. This new technology, called Zoosh™, is highly engineered software that communicates in frequencies that are inaudible to humans, but are used in nature by frogs, dolphins and other animals. With one software update, an App can now become Zoosh-powered to securely transfer data between millions of devices already in use by consumers.
"In order to deliver a secure and reliable data transaction using existing audio subsystems, we had to overcome some incredibly difficult engineering hurdles," says Naratte cofounder and CEO, Brett Paulson. "We have accomplished what some said was not possible, and the market timing could not be any better."
Naratte's Zoosh technology is engineered to be low cost, fast, secure and reliable. It can be instantly deployed to millions of mobile devices, including iPhones, Android phones, tablets and even feature phones. It requires no network connection and has no interoperability issues. Zoosh is architected to be safe for mobile payments by implementing security techniques such as creating a unique and perishable transaction IDs.
Zoosh technology is available now. Naratte's partners are currently integrating Zoosh into many different applications and environments, including phone-to-phone and phone-to-POS payments, phone-to-POS loyalty systems and digital couponing. Many other applications are in development, including instant and reliable Bluetooth and Wi-Fi authentication.
"Early adopters are already doing amazing things with Zoosh. A great example is SparkBase whose Zoosh-enabled mobile wallet application, PayCloud, recently won the 'ETA 2011 Technology Innovation Award,'" says Paulson. "Our partners are excited to enable near-field communication across millions of devices without having to wait to 2015 or beyond for mass NFC adoption."
Naratte is based in Sunnyvale, Calif., was founded in May 2009 and has 12 employees. It has received $5 million in strategic funding from an unnamed investor, and its technology is underpinned by eight patents pending. More information on Naratte and its products can be found on its new web site, also launched today at www.naratte.com.
Technology Endorsements:"PayPal is very excited about Naratte's Zoosh technology. Naratte's approach provides instant scale and low cost integration options for merchants which is a major hurdle for most mobile payment technologies. Zoosh has the potential to enable complete consumer-merchant shopping experiences." -- Laura Chambers, general manager of PayPal Mobile.
"We are extremely excited to have Naratte's Zoosh technology running on Texas Instruments' (TI) C5000™ ultra-low-power DSPs. Zoosh opens doors for every mobile customer on the planet to use their handheld device in new ways that makes their world smarter, more secure and definitely more fun. With all the innovation that's been done around wireless communication, this is one of the most creative uses of technology that I've seen." -- Matt Muse, general manager, C5000 Ultra-Low-Power DSPs, Texas Instruments.
"Zoosh is one of the most impressive and clever technologies I've seen in a long time. Being able to easily enable transactions among all types of mobile devices within the true proximity from each other, all done through a pure software-based solution, is incredibly powerful. I am a big fan of the Naratte team's obsession with the end-user experience and its knack to solve really difficult problems." -- Fay Arjomandi, head of US R&D and Incubation Centre, Vodafone Group.

Enhanced by Zemanta

Isis Chooses Austin, Texas as Initial Launch Market for Mobile Payments

Isis to Introduce Mobile Commerce in Austin, Texas

Austin Among First in U.S. to Adopt Comprehensive Mobile Commerce Experience
AUSTIN, Texas--(BUSINESS WIRE)--Isis, the mobile commerce joint venture between AT&T Mobility, T-Mobile USA and Verizon Wireless, today announced Austin, Texas is among the initial launch markets for the Isis mobile commerce program. Austin merchants and consumers are expected to be among the first in the U.S. to adopt a comprehensive mobile commerce experience in 2012.
http://www.paywithisis.com
“Austin being chosen as one of the first U.S. markets for Isis to launch is yet another strong confirmation that Austin has cemented its reputation as a national leader in innovation and technology”
“Today we are delighted to announce that Austin will be an initial Isis launch market for the Isis mobile commerce program,” said Michael Abbott, chief executive officer at Isis. “Austin is home to progressive and tech savvy consumers and merchants – a key demographic for Isis’ mobile commerce program. The city’s culture of innovation, thriving business community and early adopters make it an ideal launch market for Isis.”
Starting in the first half of 2012, Austin consumers will be able to use Isis-enabled mobile phones to make point-of-sale purchases and redeem offers at participating merchant locations throughout the city. Isis is working closely with local merchants and the Austin Chamber of Commerce to spur wide scale consumer adoption and merchant support across Austin.
“Austin being chosen as one of the first U.S. markets for Isis to launch is yet another strong confirmation that Austin has cemented its reputation as a national leader in innovation and technology,” said Mike Rollins, CCE, president of the Austin Chamber of Commerce.
Isis will bring mobile commerce to consumers and merchants by allowing them to use mobile phones to make point-of-purchase sales through the use of near-field communication (NFC) technology.
The Isis system will evolve to offer customers across the U.S. a highly secure and convenient way to pay, redeem offers and store merchant loyalty cards, all with the tap of a phone. Earlier this year, Isis announced Salt Lake City as an initial launch market in the first half of 2012.
About Isis
The joint venture is between AT&T Mobility LLC, T-Mobile USA and Verizon Wireless and is based in New York City. The venture is chartered with building ISIS™, a national mobile commerce venture that will fundamentally transform how people shop, pay and save. The Isis mobile commerce network will be available to all merchants, banks, payment networks and mobile carriers. ISIS is a trademark of JVL Ventures, LLC in the U.S. and/or other countries. Other logos, product and company names mentioned herein may be the trademarks of their respective owners.
Edelman
Tom Cook, 206-268-2238
tom.cook@edelman.com

Monday, June 20, 2011

New Mercator Advisory Group Report Explores Abundant Payment Fraud Risks


New Mercator Report: Multi-Channel Deposit Account Fraud And Vendor Solutions

Boston, MA (PRWEB) June 20, 2011

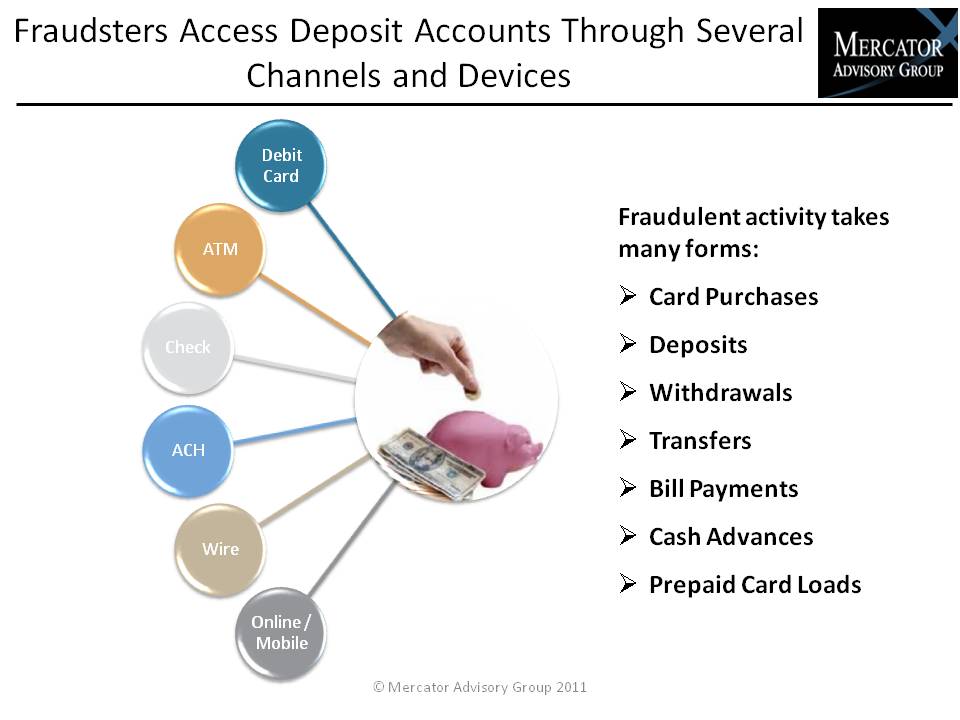
Debit cards represent only one access device through which fraudsters might attack a depository institution’s account assets. Though cards supporting “signature” debit (and, to a smaller degree, PIN debit) have enabled fraudsters to access deposit accounts through fraudulent point-of-sale or card-not-present purchases, the variety of schemes that target demand deposit accounts (DDAs) often utilize multiple channels and access devices to target the cash itself in fraudulent withdrawals and transfers.

Check fraud, ACH fraud, wire transfer fraud, ATM fraud, and online banking and mobile banking fraud (in addition to debit card fraud) collectively comprise what we’ve come to know as deposit account fraud. Since fraud schemes that target the DDA through multiple channels are proliferating, the business case for implementing a multi-channel fraud solution has never been clearer.

Mercator’s new report, Multi-Channel Deposit Account Fraud and Vendor Solutions, discusses and tries to answer these essential questions: How are these schemes being executed today by fraudsters hoping to exploit financial institutions’ vulnerabilities? How are the solutions that vendors have brought to market evolving to counter these threats?

This report reviews extant research and data to illuminate today’s DDA fraud landscape, provides case examples of recent fraud schemes that target deposit accounts, and profiles selected vendor solutions that help banks and payment processors manage fraud risk associated with at least one channel or device that accesses DDAs.

“A variety of point solutions exist in the market to address the risks associated with DDA fraud of different types in a specialized fashion, often looking at only one aspect of the usage of the instrument or channel without providing the user with a comprehensive understanding of the account-level behavior that underlies the broader customer relationship,” David Fish, Senior Analyst at Mercator Advisory Group and author of the report comments. “Some of these solutions have evolved more recently to do exactly that, or to at least aspire to multi-channel and even “enterprise-wide” fraud management. The path to a comprehensive DDA fraud solution has been paved by specialists in various channels, however, with best-of-breed solutions in debit card fraud, for instance, requiring significant modification when applied to a different type of payment instrument or access channel.”

Highlights of this report include:

Cash is a high priority for financial criminals committing payments fraud, and the variety of access devices and channels associated with demand deposit accounts makes them an increasingly attractive target.

Debit card data compromise is a chief concern to DDA risk managers due to the fact that counterfeit cards can be used both for fraudulent purchases at the point-of-sale and at ATMs for fraudulent withdrawals if the PIN has also been compromised.

Solutions vendors have typically specialized in one kind of fraud prevention over another, but the varieties of access to DDAs necessitate a broad view on the part of risk managers.

Vendors offering more comprehensive solutions tend to have aggregated point solutions that were developed by their acquisition targets – consolidation and rationalization of these has finally produced compelling results.

Strategic concerns for DDA risk include the outcome of the Durbin debate, the rising focus of fraudsters on commercial accounts, the ways in which vendors deliver and support their fraud risk management solutions, and the coming revisions to the Federal Financial Institution Examination Council’s (FFIEC) guidance for online authentication.

This report is 30 pages long and has 12 exhibits.

Companies mentioned in this report include: ACI Worldwide, Aldi, American Bankers Association, Comerica, CyberSource, Early Warning Services, Experi-Metal Inc., FFIEC, FICO, First Data, FIS, Fiserv, Global Payments Inc., Hancock Fabrics, LastPass, MasterCard, Michaels, NACHA, Pulse EFT, RSA, Verizon, Visa.

Members of Mercator Advisory Group have access to this report as well as the upcoming research for the year ahead, presentations, analyst access and other membership benefits.

TSYS Releases 2011 Research Results Regarding Consumer Debit Behavior

Debit End-To-End Solution
COLUMBUS, Ga.--(BUSINESS WIRE)--TSYS® (NYSE: TSS) today announced it has made available to the industry the first phase of results from a nationwide primary research effort focusing on consumers’ use of debit cards. It can be accessed at www.tsys.com/debit.
“There are significant changes occurring within the payments industry, particularly regarding debit”
The “TSYS & Mercator Advisory Group Debit Survey 2011” is the first in a two-part research effort focusing on consumer use and preferences for debit relative to other payment types. The goal of the survey was to identify current and potential future consumer payment preferences.
“There are significant changes occurring within the payments industry, particularly regarding debit,” said Sarah Hartman, senior director, TSYS. “TSYS determined that one of the ways we can help financial institutions better understand these changes and the many decisions facing issuers is to provide actionable information regarding current and potential future consumer payment behavior.”
More than 1,000 debit card users answered questions relating to debit card usage, payment preferences, reaction to potential debit-related fees and interest in debit card enhancements. Key findings included:
  • Debit was the preferred payment type and checks were largely a thing of the past in most point-of-sale locations.
  • Cash is the primary fall-back tender type chosen by those respondents who indicated they would reduce or completely stop using their debit cards if they were charged fees.
  • Interest was high for instant-issue cards and a secure way to enter their pin for online purchases from a debit card enhancement standpoint.
“Working alongside a leading payments provider such as TSYS on this study at such a critical juncture in the debit card industry offers an even greater depth of insight into its results,” said Patricia Hewitt, director, Debit Advisory Service, Mercator Advisory Group. “We believe the combination of survey and focus groups will allow us to gauge consumer attitudes and preferences towards debit card products and provide financial institutions with data points and directionality that can be used as they continue to evaluate and make changes to their debit and other payment products.”
The second phase of the research will include four in-person focus groups conducted in two cities. These focus groups will provide an additional layer of validation as well as help understand why consumers make certain decisions.
To obtain a full copy of the online survey results and be added to the distribution list for the results of the focus groups, please register at www.tsys.com/debit.
About Mercator Advisory Group
Mercator Advisory Group is the leading, independent research and advisory services firm exclusively focused on the payments and banking industries. We deliver pragmatic and timely research and advice designed to help our clients uncover the most lucrative opportunities to maximize revenue growth and contain costs. Our clients range from the world's largest payment issuers, acquirers, processors, merchants and associations to leading technology providers and investors.
About TSYS
TSYS (NYSE: TSS) is reshaping a new era in digital commerce, connecting consumers, merchants, financial institutions, businesses and governments. Through unmatched customer service and industry insight, TSYS creates a better experience for buyers and sellers, supporting cross-border payments in more than 85 countries. Offering merchant payment-acceptance solutions as well as services in credit, debit, prepaid, mobile, chip, healthcare, installments, money transfer and more, TSYS makes it possible for those in the global marketplace to conduct safe and secure electronic transactions with trust and convenience.
TSYS’ headquarters are located in Columbus, Georgia, with local offices spread across the Americas, EMEA and Asia-Pacific. TSYS provides services to more than half of the top 20 international banks. For more information, please visit us at www.tsys.com.

Leading (Mystery) Debit Card Company Selects inContact to Power Millions of Self-Service Customer Transactions

Company to Enhance Self-Service Offering Using inContact’s Cloud-based IVR Solution
SALT LAKE CITY--(BUSINESS WIRE)--inContact (NASDAQ: SAAS), the leading provider of on-demand call center software and call center agent optimization tools, today announced that a rapidly growing pre-paid debit card company selected the inContact interactive voice response (IVR) solution to power its customer self-service offering. The new inContact self-service application will handle approximately three million minutes of customer interactions per month, which is equivalent to the efforts of approximately 480 agents if those calls were handled in person. This represents one of the most significant customer wins in terms of future revenue potential that the company has achieved in the last twelve months.
“In the current crowded and consumer-driven market, even the world’s most recognizable brands are losing their differentiation over time”
Pre-paid debit cards provide customers with financial services that they may not have had access to before. Because the cards are the primary financial accounts for the card holders, it is important that customers can easily activate, reload and check balances at any time through the company’s phone system. Additionally, the company will use the new self-service system to cross sell and upsell customers with new products and offerings.
The company’s previous premise-based solution was not flexible enough to meet its needs and was very difficult to manage, often taking as much as two weeks to make changes to the IVR routing and recordings. The system also suffered from significant downtime. Additionally, the company could wait weeks to scale the number of ports available for callers to get through to the system. This was a significant problem, as the company has grown and the number of customers calling into the system has significantly increased.
The company selected inContact due to:
  • Flexibility: the user-friendly drag and drop interface enables system administrators to make changes on demand
  • Scalability: easily scale ports up and down with just a phone call in order to address increased customer demands
  • PCI Certification: inContact is certified as a Service Provider under the Payment Card Industry (PCI) Data Security Standard (DSS)
  • Leading self-service application: The inContact IVR solution allows customers to self-solve on basic functions like bill pay, account inquiries and more. When the call center is closed, the IVR adds an extra level of convenience by enabling customers to take care of business after hours
  • Integration: The inContact cloud-based IVR seamlessly integrates with other technologies and can be deployed fast, without any additional equipment purchases
“In the current crowded and consumer-driven market, even the world’s most recognizable brands are losing their differentiation over time,” said Paul Jarman, inContact CEO. “In order to drive sustainable business growth over the long term, companies need to differentiate through service. IVR self-service is typically the first touch point customers have with a company, and it’s extremely important that it enables them to get what they need as efficiently and as cost effectively as possible.”
The cloud-based IVR market is growing quickly. According to DMG Consulting, “There are many compelling reasons why end users are adopting hosted IVR technology at a rapid rate, while revenues from premise-based IVR systems are expected to shrink. Scalability is one reason; availability of touch-tone and speech recognition resources another; avoidance of large up-front capital and implementation costs a third. Pace of innovation and ease of upgrades are additional factors.”1
Concluded Jarman, “We look forward to working with this debit card provider to help them provide a brand-building and differentiated self-service experience for their customers.”
1 DMG Consulting, Hosted Contact Center Infrastructure Market Report, 2010
About inContact
inContact (NASDAQ: SAAS) helps call centers around the globe create profitable customer experiences through its powerful portfolio of cloud-based call center software solutions. The company’s services and solutions enable call centers to operate more efficiently, optimize the cost and quality of every customer interaction, create new pathways to profit and ensure ongoing customer-centric business improvement and growth. To learn more, visit www.inContact.com.
inContact® is the registered trademark of inContact, Inc. All other marks are the property of their respective owners.

Elavon Introduces SAFE-T Suite Point-to-Point Encryption and Tokenization Solution

Secure, Flexible Comprehensive Solutions Protect Data and the Bottom Line

HITEC 2011  Booth #425
http://www.elavon.comATLANTA--(BUSINESS WIRE)--Elavon, a wholly owned subsidiary of U.S. Bancorp (NYSE: USB) and a leading global payments provider, today releases SAFE-T Suite, its Secure and FlexibleEncryption and Tokenization portfolio of products and services that helps companies protect data at every point in the transaction lifecycle: in use, in transit and at rest. The solution also eases the burden of PCI compliance audits and helps reduce the total cost of card acceptance.
“SAFE-T Suite considers every requirement an enterprise may need to meet stringent security standards and protect the bottom line – from ROI analysis to PCI Audit Managed Services, our experts perform solution design and implementation support because we understand that security is a process, not a product.”
SAFE-T Suite supports point-to-point encryption (P2PE, also referred to as end-to-end encryption) and protects data from the earliest point in the transaction lifecycle utilizing VeriFone’s hardware-based tamper-resistant security module. Actual cardholder data never enters the payment stream, substantially mitigating the complexities of PCI compliance while meeting stringent security standards.
The encrypted data travels across the networks to Elavon’s secure data center where it is decrypted and sent to the card networks for authorization. Merchants also have the flexibility to utilize Fusebox, Elavon’s secure, hosted payment gateway that features multi-point connectivity to an extensive list of Fusebox-certified processors, thereby providing a consistent method for P2PE regardless of acquiring endpoints.
SAFE-T Suite also supports tokenization, which creates a unique Token ID that replaces cardholder data on the response transaction, protecting data at rest and allowing subsequent transactions and adjustments to be securely processed whenever the card number associated with the transaction needs to be used again. Elavon hosts and maintains the token vault in its secure data center, which removes a point of vulnerability for enterprise customers.
Designed with flexibility in mind, Elavon supports multiple configurations to simplify PCI and even extend the life of legacy POS systems while employing a consultative, tailored approach for SAFE-T Suite implementation to ensure that every security consideration and compliance requirement is met. Further, Elavon makes it simple for businesses to work with a single provider for both P2PE and tokenization while extending the opportunity to utilize Elavon as an acquiring host or to connect to multiple processors using Fusebox.
“Our comprehensive solution combines over 20 years of global processing and gateway experience with our stable, redundant Stratus systems and the industry’s most knowledgeable, responsive people,” said Marianne Johnson, newly named Executive Vice President of Global Product & Innovation, of Elavon. “SAFE-T Suite considers every requirement an enterprise may need to meet stringent security standards and protect the bottom line – from ROI analysis to PCI Audit Managed Services, our experts perform solution design and implementation support because we understand that security is a process, not a product.”
To learn more about SAFE-T Suite, visit Elavon at HITEC booth #425.
About Elavon: Elavon’s Global Acquiring Solutions organization is a part of U.S. Bancorp. Elavon provides end-to-end payment processing services to more than one million merchants in the United States, Europe, Mexico, Brazil, Canada and Puerto Rico. Solutions include credit and debit card processing, electronic check services, gift cards, multi-currency support, and cross-border acquiring. Elavon’s solutions meet the needs of merchants in specialized markets including small business, retail, hospitality/T&E, health care, education and the public sector and are marketed through multiple alliance partner channels including financial institutions, trade associations and ISOs. For more information about Elavon visit www.elavon.com.

Saturday, June 18, 2011

iPhone and Android Owners Trust Apple and Google with Mobile Wallet over Visa/MasterCard

iPhone Owners Trust Apple With Mobile Wallet Over Mastercard and Visa

Posted by Josh Smith -GottabeMobile.com| June 17,2011 

Google is hoping that millions of Android users will jump at the chance to turn their smartphone into a wallet with Google Wallet,but based on the results of a survey by Retrevo Google is facing an uphill battle. Not only are iPhone owners more interested in a mobile wallet than Android owners,but only 21% of the surveyed users are interested in paying with their phones. The most surprising result from the survey was that most users would trust Apple or Google to run their mobile wallet over MasterCard,Visa and American Express.
Apple Mobile Wallet
While the preference to have Google and Apple run their mobile wallet is a surprise,we aren’t shocked by the choice,especially given the numerous credit card breaches which reflect poorly on the ability of credit card companies to provide a secure mobile wallet. You’re not reading it wrong,iPhone owners would pick Apple to handle their credit and debit transactions over the current credit can debit card companies.
This preference also ties in closely with the mobile operating system currently in use by the respondent. This points to a desire to have a mobile wallet service built into the hardware and software,rather than added on with a case and a third-party app.
Ready for a Mobile Wallet
The survey also showed that 40% of iPhone owners are interested in NFC,or mobile wallet,technology built into their nextphone,compare to 24% of Android users. This could pose an issue for Google Wallet if Apple decides to introduce NFC technology in the iPhone 5 and launch the Apple Wallet. If you think about it,Apple has an upper hand thanks to the 200 million iTunes users that have already shared payment information with Apple.
NFC and Mobile Wallet Survey
Unfortunately for those of us who can’t wait to start using our phones to pay,the bigger issue is gaining enough push from mainstream users to reach critical mass for merchants to accept smartphone NFC payments. How hard will this be? Considering that 26% of the respondents had no clue what NFC was and 53% aren’t interested in using their phone as a wallet —it’s going to be an uphill battle.
Even though we think Google Wallet has a chance at succeeding,the service will face pressure from users and retailers that don’t understand NFC. For Google Wallet and other alternatives to succeed it may take the power of Apple,and Steve Jobs,to explain to users why they “need”a mobile wallet. Perhaps we’ll see this in the iPhone 5.

Disqus for ePayment News