Wednesday, February 8, 2012

MasterCard Establishes Relationship with Silver Tail Systems to Combat Online Fraud

Image representing Silver Tail Systems as depi...
Image via CrunchBase

Alliance will enable online merchants to more effectively differentiate fraudsters from legitimate consumers
PURCHASE, N.Y.--()--MasterCard Worldwide and Silver Tail Systems, a leading provider of web session intelligence, announced today a new exclusive relationship that will focus on leveraging and creating innovative solutions to help combat online fraud.
“Web-based navigation-centric solutions view the HTTP stream of a website and analyze in real time the traffic and Web sessions by user and IP addresses”
The companies’ collective expertise will enable merchants to differentiate fraudsters from legitimate consumers in real-time during the online shopping experience.
With eCommerce transactions reaching record levels*, both merchants and consumers benefit from identifying the safest and smartest ways to conduct online transactions.
By combining Silver Tail Systems’ technology with MasterCard’s extensive payments experience and insights, merchants will be better equipped to spot malware or robotic (“bots”) activity originating from personal computers or smart phones attacking their online payments systems.
“Online fraud resulting from malware, viruses and criminal-controlled bots is a serious concern for both merchants and consumers,” says Johan Gerber, Group Head, Global Network Products for MasterCard Worldwide. “With the increased sophistication of these fraud attacks, merchants are finding it more difficult to distinguish between good customers and criminals. Our relationship with Silver Tail Systems allows us to extend beyond the traditional fraud detection methods and provide merchants with a strong defense against fraud, while improving the consumers’ online experience.”
"We are excited to join forces with MasterCard to help reduce fraud for online merchants," says Tim Eades, CEO of Silver Tail Systems. "eCommerce merchants have broadened their focus to embrace the notion of customer interactions, not simply customer transactions. Smart phones, social networks, and app stores represent new catalysts that are forcing merchants to rethink customer interaction with their web presence. Cybercriminals are also exploiting these trends and traditional security tools may not be capable of keeping pace. We provide that granular level of visibility and security throughout consumers' entire online shopping experience, without requiring modification to the end user's device or the back-end website infrastructure."
“Web-based navigation-centric solutions view the HTTP stream of a website and analyze in real time the traffic and Web sessions by user and IP addresses,” says Avivah Litan, Vice President and Distinguished Analyst at Gartner Research. “This method has been successfully used by Gartner clients to spot malware-based activity that shows up as abnormally quick navigation or navigation that doesn't follow normal human patterns and behavior. It has also been used successfully to identify fraud rings and to gain visibility into attacker patterns and behavior.”
Through the new alliance, which is exclusive within the payments industry, MasterCard and Silver Tail Systems will immediately work together to bring innovative fraud solutions to online merchants in the U.S., while exploring future opportunities to expand the scope and reach of the relationship.
* In 2011, U.S. retail e-commerce spending reached a record $161.5 billion, a 13-percent increase from 2010, according to comScore, which measures digital data.
About MasterCard
MasterCard (NYSE: MA) is a global payments and technology company. It operates the world’s fastest payments processing network, connecting consumers, financial institutions, merchants, governments and businesses in more than 210 countries and territories. MasterCard’s products and solutions make everyday commerce activities – such as shopping, traveling, running a business and managing finances – easier, more secure and more efficient for everyone. Learn more at http://www.mastercard.com/, follow us on Twitter @mastercardnews or join the conversation on The Heart of Commerce Blog.
About Silver Tail Systems
Silver Tail Systems is a leading provider of web session intelligence and protects the world’s leading websites against fraud and cyberattacks at the navigation layer. Silver Tail Systems' award-winning solutions are made possible by the unmatched expertise of its management and technology teams, who bring deep experience, know-how and personal commitment to protect their customers' businesses against online fraud. For more information, visit Silver Tail Systems at www.silvertailsystems.com.

Discover U.S. Spending MonitorSM Consumer Confidence Jumps in January


Consumers’ Views About the Economy and Their Finances Are Improving
RIVERWOODS, Ill.--()--Consumer confidence jumped in January, with more consumers saying the general economy and their personal finances are improving. The Discover U.S. Spending Monitor, a 4-year-old daily poll tracking economic confidence and spending intentions of nearly 8,200 consumers throughout the month, recorded a 5.5-point jump from the previous month to 90.5. This is the first time since May 2010 that the index has topped 90.
Nearly 30 percent of consumers felt the overall economy is getting better, a jump of more than 6 percentage points from December and the highest figure in the last year. At the same time, those who reported their personal finances were improving rose nearly 5 percentage points to 23 percent – also the highest figure since February 2011.
The percentage of people who rated the U.S. economy as poor also declined from the previous month, down 2 percentage points to 56 percent. At the same time, the percentage of people who rated the economy as good or excellent exceeded 11 percent, an increase of more than 2 percentage points from the month before and the highest percentage for the Monitor since September 2008.
Views of Personal Finances Improve; More Money Left Over
Consumer sentiment toward their personal finances showed a marked improvement, while more consumers also reported more money left over at the end of the month:
  • Consumers from households of all incomes reported a brightening attitude toward their personal finances, with those from households earning between $40,000 and $75,000 annually seeing the biggest jump in sentiment. Of that group, nearly 27 percent said their personal finances were improving, up more than 7 points from the month before. In comparison, of consumers from households with less than $40,000 in annual income, nearly 15 percent reported they feel more positive about their personal finances, up nearly 4 points from the month before.
  • 47 percent of consumers reported they had money in their pockets after paying bills last month, an increase of 2 points from the month before.
  • Of those who reported having money left over, more than 16 percent said that amount was greater than they had the previous month, a jump of nearly 6 points from December.
Spending Intentions Remain Steady
Consumers reported they spent markedly less in January compared to the previous month, which is typical spending behavior after the holidays. Despite the increase in the number of consumers having money left over after paying bills, consumers say they will hold the line on spending next month.
  • 54 percent said they would spend about the same next month, compared to just 43 percent who said that last month. In addition, the percentage of people who said they would spend more did not change.
  • The percentage of people who said they would spend less also declined: 21 percent reported they would spend less, a decrease of 10 percentage points from the month before.
Consumers Stay Conservative with Discretionary Spending Plans
Consistent with last month’s data, consumers reported this month that they intend to be conservative with their discretionary spending.
  • Just 7 percent said they would spend more next month on discretionary personal items like going out to dinner or the movies, which is the lowest percentage since January 2011. In addition, 49 percent said they would spend less next month on discretionary personal items, an increase of 1 percent, while 41 percent said they would spend about the same as the prior month, an increase of 3 points.
  • In addition, 45 percent reported they would spend less next month on major personal purchases like a vacation, which is down 2 percentage points from the month before, while 40 percent said they plan to spend the same, up 3 points from December.
  • Household expenditures are expected to remain largely the same in February: 37 percent planned on spending more in the next 30 days, the same as last month, while 9 percent said they would spend less, an increase of 1 percentage point from the month before. Fifty-two percent said they would spend the same amount as the month before, a decrease of 1 percentage point from the month before.
About Discover
Discover Financial Services (NYSE: DFS) is a direct banking and payment services company with one of the most recognized brands in U.S. financial services. Since its inception in 1986, the company has become one of the largest card issuers in the United States. The company operates the Discover card, America's cash rewards pioneer, and offers personal and student loans, online savings accounts, certificates of deposit and money market accounts through its Discover Bank subsidiary. Its payment businesses consist of Discover Network, with millions of merchant and cash access locations; PULSE, one of the nation's leading ATM/debit networks; and Diners Club International, a global payments network with acceptance in more than 185 countries and territories. For more information, visithttp://www.discoverfinancial.com.

Virtual Piggy Announces New Mobile E-Commerce Application for Apple iOS Devices and NFC Plans

Image representing Business Wire as depicted i...
Image via CrunchBase

Innovative Solution For Online Purchasing For Kids Now Available On iPhone and iPad
PHILADELPHIA--()--Virtual Piggy, Inc. (OTCBB: VPIG), the innovator in safe-online youth purchasing, today announced the release of its mobile iOS application, which allows parents and kids to manage their Virtual Piggy accounts on their Apple phones and tablets. Virtual Piggy offers a secure, COPPA compliant, e-commerce solution to enable kids under 18 to make online purchases.
“The Virtual Piggy app brings our secure online payment method to the platforms where kids spend the majority of their time.”
Kids between the ages of 8 and 18 have more than $50 billion in annual spending power and yet when it comes to online purchases they either have no ability to spend or they have their parent’s credit card. Virtual Piggy provides technology that gives kids the ability to shop online in a controlled environment that parents can feel comfortable about.
“Kids are very comfortable with e-commerce and over a third of kids 8-11 now have their own mobile device and that number is rising,” said Virtual Piggy Executive, Catherine Williams. “The Virtual Piggy app brings our secure online payment method to the platforms where kids spend the majority of their time.”
The introduction of the Virtual Piggy mobile application is an integral part of the company’s plans to bring their family approved e-commerce solution to the global U18 market, whether they are shopping online using mobile devices or PC’s, or in-store with the integration of NFC technology.
The application is available for download at VirtualPiggy.com and in the iTunes store for no charge.
About Virtual Piggy, Inc.
Virtual Piggy, Inc. delivers a technology platform designed for the management of the under 18 age group in the global online market. Virtual Piggy’s technology enables online businesses to function in a manner consistent with the Children’s Online Privacy Protection Act (COPPA) and similar international children’s privacy laws. Virtual Piggy’s technology enables the under 18 audience to play, transact and socialize in a secure online environment guided by parental permission, oversight and control. For more information about Virtual Piggy, please visit the Company’s website at: www.virtualpiggy.com

Cashplus: New Cheaper and Easier Alternative to 'Free' Banking


Cashplus’ new Direct Debit service has a number of unique benefits, including:
  • Low balance alerts – If it looks like a Direct Debit is going to bounce, Cashplus® will alert you by SMS and email before the payment is due
  • Instant loans for just 50p a day – If you don’t have the money, Cashplus® offer a loan up to £1,000 to guarantee your bill is paid on time
  • No penalty fees (Debit Protect) – If a Direct Debit can’t go through Cashplus® won’t hurt your pockets further by imposing a penalty
Already trialled with over 100,000 existing customers, Cashplus® is likely to appeal to a wide range of people. It is particularly attractive to those without bank accounts who, until now, have not been able to access the discounts that many companies offer to customers paying by Direct Debit.
To mark the launch, between 8th February and 31st March, Cashplus® customers who set up and pay a Direct Debit via their Cashplus® account will be entered into a prize draw, the lucky winner having their rent or mortgage paid for a year (up to £10,000).
Richard Wagner, Cashplus® CEO said; “A common reason for people getting into debt is that a Direct Debit bounces, sometimes simply because another payment hasn’t gone through. The bank then imposes a penalty, as high as £24, which puts the customer further into the red and into a spiral of debt as more payments then can’t be met, just at a time when money is tightest.
“We have built this product by talking to customers and trying to address the complaints they have about banks and financial institutions. We believe this new service is truly unique. One of our key drivers has been to make all our costs completely transparent, so although the account is not ‘free’ the actual cost, taking account of typical penalties paid by bank customers, is small.”
To out more and enter the prizedraw go to: www.facebook.com/cashplus.

USA Technologies Inks New Three-Year Relationship with Elavon, Inc.

U.S. Bancorp logo
Image via Wikipedia

MALVERN, Pa.--()--USA Technologies, Inc. (NASDAQ: USAT), a leader of wireless, cashless payment and M2M telemetry solutions for self-serve, small-ticket retailing industries, announced that effective November 2011, the company has extended a ten-year relationship for an additional three-years with Elavon, a wholly-owned subsidiary of U.S. Bancorp (NYSE: USB), and a leading global payments provider. Through the delivery of world-class service and competitive pricing, the agreement provides USA Technologies with Elavon’s support to continue with its growth plans.

“This agreement with Elavon is not only important from a business standpoint—helping us towards our goal of profitability and ensuring our services remain positioned for continued growth—but it’s important because it further underlines our commitment to our customers and the consumers who utilize our service”
“We’re very pleased to formalize this new agreement with Elavon, and enter our second decade of doing business together,” said David M. DeMedio, Chief Financial Officer of USA Technologies, Inc. “Our work with Elavon and their commitment to our growth strategy puts us in a position to meet both our long and short-term objectives. We believe that it is also further validation of USA Technologies’ position as a leader in wireless, cashless payments for the self-serve, small-ticket industries.”
“Continuing our relationship with USA Technologies provides Elavon with an opportunity to drive commerce and growth for the small ticket market that USA Technologies represents,” said Tom Boyer, President of Elavon North America. “We are enthusiastic to align with such a well-respected market leader.”
With this new agreement, USA Technologies has reached another milestone along the anticipated path towards profitability consistent with the new priorities the Company recently articulated in a letter to its shareholders. With a safe, secure card-processing provider, USA Technologies has a solid foundation that will support both improvements in functionality as well as a continued increase in customers, connections and resulting transactions processed on the Company’s ePort Connectservices.
“This agreement with Elavon is not only important from a business standpoint—helping us towards our goal of profitability and ensuring our services remain positioned for continued growth—but it’s important because it further underlines our commitment to our customers and the consumers who utilize our service,” concluded DeMedio. “By working with a world-class business partner like Elavon, we increase our value to our customers by providing them the best possible service at competitive rates, and ensuring that their customers have a seamless, enjoyable payment transaction at the point of sale.”
About USA Technologies:
USA Technologies is a leader in the networking of wireless non-cash transactions, associated financial/network services and energy management. USA Technologies provides networked credit card and other non-cash systems in the vending, commercial laundry, hospitality and digital imaging industries. The Company has been granted 79 patents and has agreements with Verizon, Visa, Compass, Crane and others. Visit our website at www.usatech.com.
About Elavon (www.elavon.com):
Elavon’s Global Acquiring Solutions organization is a part of U.S. Bancorp (NYSE: USB). Elavon provides end-to-end payment processing services to more than 1.2 million merchants in the United States, Europe, Mexico, Brazil, Canada and Puerto Rico. Solutions include credit and debit card processing, electronic check services, gift cards, multi-currency support, and cross-border acquiring. Elavon’s industry leading solutions meet the needs of merchants in specialized markets including small business, retail, hospitality/T&E, health care, education and the public sector and are marketed through multiple alliance partner channels including financial institutions, trade associations and ISOs.

Tuesday, February 7, 2012

2012 Credit Card Processing Trend Predictions Released by CardPaymentOptions.com

CardPaymentOptions.com has released its 2012 predictions for the payment industry and the focus for this upcoming year is mobile processing.

Santa Monica, CA (PRWEB) February 07, 2012

CardPaymentOptions.com has released its 2012 predictions for the payment industry and the focus for this upcoming year is mobile processing. With the boom of near field communication, mobile payment systems, as well as quick response (QR) codes, CardPaymentOptions.com is confident it will be a very technology-driven year for the processing industry.
Mobile Processing
Square and GoPayment have been on the forefront of mobile phone credit card processingtechnology for the last 12 months and CardPaymentOptions.com is expecting that to continue. With Square announcing it has reached over one million accounts, the growth so far has surpassed many analyst expectations. GoPayment has publicized their step into the international arena with services being offered in Canada later in 2012.
Near Field Communication
Major corporations like Google have jumped into the payment processing industry and started pushing NFC technology embedded in smartphones. Google has partnered with Citi and MasterCard and are betting heavily that the smartphone will soon be a replacement for a traditional wallet; holding payment methods, discount cards, even personal identification.
“The payment industry has been very consistent for the past 30 years, and the banks and processors have typically held the upper hand over merchants.” Said Phillip Parker, CEO of CardPaymentOptions.com, “With the advent of new technology and multiple competitors entering the payment landscape, the power is starting to shift and merchants are being presented with better processing options that fit their specific needs.”
The news for 2012 is not all good, however. CardPaymentOptions.com predicts that with the ever-adjusting regulations and the pressure on processors to compete with new technologies, merchants may start to see additional fees added to their existing accounts. Processors may also choose to hike rates, which according to most contracts they have the ability to do whenever they see fit.
For a complete list of predictions, visit Top Credit Card Processing Trends for 2012.
About CardPaymentOptions.com
CardPaymentOptions.com was founded for the purpose of educating business owners about the misinformation and unethical practices many processing companies are engaged in. They provide in-depth analysis on over 100 processing companies, including an A to F rating for each business. Based on the extensive reviews, CardPaymentOptions.com has compiled a list of recommended merchant account services that fit specific business needs.
###

YESpay and YES-wallet.com Partner to Deliver Cloud Based NFC Contactless Payment Service for NFC Smartphones


Pouch wallet
Quote startPouch - World's first cloud service based NFC contactless card emulation service.Quote end

London, UK: YESpay International and YES-wallet.com Ltd, February 6, 2012 Two companies, YESpay International Limited and YES-wallet.com Limited have built a cloud based payment platform using Near Field Communication (NFC) global standard technology. YESpay and YES-wallet today announced the launch of cloud-based NFC contactless card emulation services conforming to PayWave and PayPass standards offering a more convenient and efficient payment solution for merchants and consumers.


Two companies, YESpay International Limited and YES-wallet.com Limited have built a cloud based payment platform using Near Field Communication (NFC) global standard technology. YESpay and YES-wallet today announced the launch of cloud-based NFC contactless card emulation services conforming to PayWave and PayPass standards offering a more convenient and efficient payment solution for merchants and consumers.
By integrating YES-wallet pouch digital wallet service with YESpay EMBOSS payment service, both companies will provide a cloud service based e-Money/pre-paid/gift-card payment platform that allows provision of convenient and efficient payment methods on NFC smartphones based on Visa PayWave and MasterCard PayPass standards.
Both companies have been focusing on development and provision of Near Field Communication products that comply with NFC global standard.
The partnership allows e-Money (pre-paid gift-card) related business, merchant, and mail order house to implement contactless card payment system without having to make heavy upfront investment by using the Pouch cloud service. YESpay will contribute by providing “payment terminals based on NFC reader/writers” and providing “EMBOSS payment processing services to cultivate and manage merchants” and YES-wallet will contribute by providing “PayWave or PayPass standard virtual payment cards cloud system via its Pouch digital wallet service.”
In the near term, both companies will focus on e-Money payment service based on PayWave/PayPass contactless smart card for closed-loop e-Money applications on behalf of Enterprises. In the future, the partnership expects to form partnerships with bank card issuers and enterprises issuing Visa and MasterCard.
YESpay regularly processes millions of cardholder payments for its merchants and predicts mobile payment will attract customers and merchants alike looking to experience the speed, ease and convenience of paying with their mobile phone.
EPOS solutions providers, Mobile App and web developers can contact YESpay International Limited via sales(at)yes-pay(dot)com or 0871 221 9510 to request integration guides and obtain more information about the YESpay mobile payments strategy.
About YESpay International Limited:
YESpay, a global card payments service company, provides highly secure Internet, EMV Chip & PIN, contactless and gift card payment processing services to independent and multi-chain merchants. Through EMBOSS™, the YESpay Managed Payment Service, merchants can quickly accept integrated card payments within EPOS, kiosks, hospitality and e-commerce systems with minimal capital investment and low on-going services costs. EMBOSS is an on-line IP-based payment processing service that has been generically pre-accredited by major Card Acquirers in Europe and North America (including Chase Paymentech, First Data Merchant Service (FDMS), Barclaycard Business, HSBC, HBOS, Lloyds Cardnet, Streamline, Ulster Bank, Elavon, PBS, Amex and Diners). In addition, the YESpay EMBOSS service is fully end to end certified to Payment Card Industry Data Security Standards (PCI DSS) Level 1 as mandated by Visa and MasterCard. The YESpay EasyV-Suite of card payment products is innovative and cost-effective for EPOS, Kiosk, Hospitality, Mobile and Internet environments. With the YESpay EMBOSS card payment service, merchants can perform card payments in both card-present and card-not-present environments.

Visa Tops One Million Chip Cards in the U.S.

A credit card, the biggest beneficiary of the ...
Image via Wikipedia

Visa to support continued industry adoption with enhanced Visa Chip Services

SAN FRANCISCOFeb. 6, 2012 /PRNewswire/ -- Visa Inc. (NYSE: V) today announced that U.S. financial institutions have reported issuing an estimated one million Visa-branded, EMV chip-enabled cards as of December 31, 2011, demonstrating the significant progress the industry is making toward implementing Visa's U.S. chip roadmap.(1),(2)  In August 2011, Visa announced plans to accelerate mobile innovation and the adoption of EMV contact and contactless chip technology in the U.S.
"Migrating the U.S. market to chip will help build an infrastructure for accepting NFC mobile payments, enhance international acceptance and reduce fraud," said Stephanie Ericksen, head of authentication product integration, Visa Inc. "Since announcing our roadmap last year, we have seen strong interest among U.S. issuers large and small to invest in chip technology, as today's milestone shows. The progress is all the more significant considering that just 18 months ago, there were no Visa-branded EMV contact chip cards issued in the U.S."
EMV chip technology refers to the microchip that is embedded in a credit or debit card, or even a mobile device. Sometimes misleadingly referred to as "chip and PIN," EMV chip is commonly deployed with a variety of cardholder verification methods including signature as well as PIN.  Under Visa's approach, both methods, as well as "no signature required," will continue to be available to issuers and merchants in the U.S. according to their preferences. The critical security advancement is the EMV chip, which protects the cardholder by generating a unique code every time it is used, effectively eliminating the problem of counterfeit cards. The same chip technology also enables mobile NFC payments.
Consumer EMV chip card programs are available from financial institutions such as Chase Card ServicesState Employees' Credit UnionUnited Nations Federal Credit UnionU.S. Bank, and Wells Fargo. The growing adoption of chip technology in the U.S. has been facilitated by Visa's flexible approach to cardholder verification, which provides choices to issuers and merchants as they deploy chip cards and terminals that support signature or PIN or a combination of the two, based on the unique needs of their customers.
"In 2011, Wells Fargo led the way with an EMV smart card pilot to 15,000 customers who travel frequently to countries where chip-based payments is the standard," said Eric Schindewolf, vice president of product development for Wells Fargo Consumer Credit Card. "Based on the overwhelming success of the pilot, we are now considering making this program more widely available."
Visa Chip Services
To support continued issuer adoption of chip payment technology, Visa is introducing Visa Chip Services, a suite of new and existing solutions to help issuers implement programs using EMV chip technology, including NFC-based mobile payments. Built on Visa's extensive chip expertise, Visa Chip Services will help issuers adopt the latest payment technologies efficiently and with minimal infrastructure investment. Several U.S. issuers have already taken advantage of Visa's services to introduce chip card programs, primarily targeted to international travelers, which represents a first step in a more broad-based migration. More than a dozen programs have been introduced since 2010. As issuers become more familiar with chip technology and leverage the groundwork they have already created, interest in more broad-based card programs as well as mobile NFC-based payments is growing as well.
"State Employees' Credit Union was able to build on Visa's expertise and solutions to engage quickly and launch an EMV chip card program in a matter of months, not years," said Leanne Phelps, senior vice president, Card Services, State Employees' Credit Union. "The jump-start helped us to be a leader and provide our members the products and services they want and need."
In addition to consulting services, best practices and testing tools, Visa is able to provide chip data processing and authentication services for issuers who have not made the back-end host system upgrades to be able to recognize and process more complicated chip transaction data.
The services suite has four key components:
  • Visa Chip Authenticate is a service where Visa validates the EMV cryptogram on behalf of the issuer, minimizing the need for issuers to make authentication-related host system changes to verify chip transaction data. Issuers can choose to use this solution as a long term solution or on a interim basis while host system changes are in progress.
  • Visa iCVV Convert is a chip data conversion and verification service that reduces chip data-related issuer and processor host system changes by converting the chip-based ICC Card Verification Value (iCVV) to the magnetic stripe-based Card Verification Value (CVV) and removing the chip data prior to sending the transaction to the issuer for review and response.
  • Visa Streamlined Chip Setup accelerates issuers' time to market through a turnkey setup and testing service for issuers that require a streamlined online-only EMV compliant solution.
  • Visa Custom Chip Setup provides issuers requiring online and offline PIN capability with customized guidance on key implementation decisions to develop an optimal chip issuance program.
Visa Chip Services is consistent with a set of implementation recommendations Visa introduced last month in order to help financial institutions and merchants make informed decisions as they evaluate competitive vendor offerings. The recommendations focus on using online processing rather than offline functions that can increase cost and complexity for chip card programs.
About Visa Inc.: Visa is a global payments technology company that connects consumers, businesses, financial institutions and governments in more than 200 countries and territories to fast, secure and reliable digital currency. Underpinning digital currency is one of the world's most advanced processing networks—VisaNet—that is capable of handling more than 20,000 transaction messages a second, with fraud protection for consumers and guaranteed payment for merchants. Visa is not a bank and does not issue cards, extend credit or set rates and fees for consumers. Visa's innovations, however, enable its financial institution customers to offer consumers more choices: pay now with debit, ahead of time with prepaid or later with credit products. For more information, visit www.corporate.visa.com.
(1) The one million cards figure is based on Visa issuer estimates.
(2) EMV (Europay, MasterCard, Visa) is a global standard for payment cards, terminals and transactions
based on chip technology.

SOURCE Visa Inc.

Smart Card Alliance White Paper Explores Possibilities for NFC in Transit Industry


SOURCE: The Smart Card Alliance
February 06, 2012 13:15 ET
PRINCETON JUNCTION, NJ--(Marketwire - Feb 6, 2012) - With Near Field Communication (NFC)-enabled handsets poised to exceed 100 million in 2012, the Smart Card Alliance Transportation Council today announced a new white paper examining how the transit industry can best make use of this popular new technology.
"One of the major challenges facing transit agencies today is how to capitalize on the ever-growing popularity of mobile phones with a solid mobile strategy," said Craig Roberts, Utah Transit Authority, and chair of the Transportation Council. "This white paper builds on the knowledge base developed in earlier white papers to foster a greater understanding of NFC technology, explain its role in the transit industry, and shed light on key issues facing the transit industry in developing a mobile strategy."
The white paper, "NFC and Transit," is available for free download by visitinghttp://www.smartcardalliance.org/pages/publications-near-field-communication-and-transit. It explores the use of NFC for payment, transit ticketing and non-payment transit information applications. Topics include:
  • Transit mobile applications overview
  • NFC applications that can benefit transit including payment, ticketing and information applications
  • The NFC ecosystem and stakeholder roles
  • Key considerations for developing a mobile strategy
  • Examples of NFC pilot projects in New Jersey, London, San Francisco and Germany
"In order to fully realize the benefits of NFC technology, transit agencies need to immerse themselves into the operational details of the NFC ecosystem and thoroughly understand the technology and business models," said Randy Vanderhoof, executive director of the Smart Card Alliance. "This white paper is another piece of the puzzle in terms of fully educating the industry on the ins and outs of NFC."
Participants involved in the development of this white paper included: Accenture; ACS, A Xerox Company; American Express; Ashok Joshi; Collis; Connexem Consulting; Cubic Transportation Systems; Dallas Area Rapid Transit (DART); Giesecke & Devrient; HP Enterprise Services; Identive Group; Infineon Technologies; INSIDE Secure; JPMorgan Chase; LTK Engineering Services; MasterCard Worldwide; MTA New York City Transit; NJ TRANSIT; NXP Semiconductors; OTI America; Quadagno & Associates; Southeastern Pennsylvania Transportation Authority (SEPTA); U.S. Department of Transportation/Volpe Center; VeriFone; Visa Inc.; Washington Metropolitan Area Transit Authority (WMATA).
For more resources, visit the Transportation Council's Open Payment Resources webpage. For more on transit and other news, join the LinkedIn group Smart.Transit, and follow the Smart Card Alliance on Twitter @SmartCardOrgUSA, and Facebook at Smart Card Alliance.
Transit and NFC topics are on the agenda this week at the Smart Card Alliance 2012 Payments Summit, February 8th -10th, 2012 at the Hilton Salt Lake City Center in Salt Lake City, Utah. Visit the 2012 Payments Summit event page for more information.
About the Smart Card Alliance Transportation CouncilThe Smart Card Alliance Transportation Council is focused on promoting the adoption of interoperable contactless smart card payment systems for transit and other transportation services. The Council is engaged in projects that support applications of smart card use. The overall goal of the Transportation Council is to help accelerate the deployment of standards-based smart card payment programs within the transportation industry.
About the Smart Card AllianceThe Smart Card Alliance is a not-for-profit, multi-industry association working to stimulate the understanding, adoption, use and widespread application of smart card technology.
Through specific projects such as education programs, market research, advocacy, industry relations and open forums, the Alliance keeps its members connected to industry leaders and innovative thought. The Alliance is the single industry voice for smart cards, leading industry discussion on the impact and value of smart cards in the U.S. and Latin America. For more information please visit http://www.smartcardalliance.org.

84.5% Have Privacy Concerns over Google Personalized Search


In January 2012, Google announced it would start integrating content from its social network, Google+, into users' search results. This has led to some concerns about privacy and whether the content from Google+, which is not as widely used as Facebook and Twitter, serves as an accurrate enough representation of the conversations taking place in social media. 


MasterCard Opens East African Regional Headquarters in Nairobi, Kenya


Global Payments and Technology Company Announces Official Presence across the Region

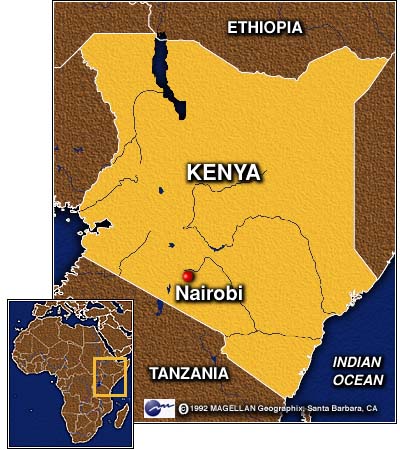
NAIROBI, Kenya--()--MasterCard Worldwide, a global payments and technology company, today launched its official East African regional headquarters in Nairobi, Kenya. This development brings the number of MasterCard offices across the African continent to five, with other offices operational in Cairo, Casablanca, Lagos, Johannesburg and now Nairobi.
“Nairobi’s reputation as an African commerce, trade and development hub made it a strategically sound location for MasterCard to establish its regional headquarters. We believe it is a natural recognition of Kenya’s role as the financial heart of the East Africa region,” says Daniel Monehin, Area Head, East & West Africa and Indian Ocean Islands, MasterCard Worldwide.The Right Honorable Raila Odinga, Prime Minister, Republic of Kenya welcomed MasterCard’s announcement. “We are pleased to welcome MasterCard to East Africa and in particular to Kenya, as we see the region’s growth path continue. MasterCard’s products will see the benefits of inclusion into the financial system extend to many more East Africans, giving them the opportunity to transact electronically with people and companies and so keep their precious money safe and secure, helping to build prosperity for their future.”
The Nairobi office will act as MasterCard’s liaison office for customer banks, business associates and consumers in its main markets of Kenya, Tanzania, Mauritius, Ethiopia and Uganda, as well as across the rest of the East African region, bringing the organisation’s knowledge of electronic payments best practice to these markets.
This will include a significant emphasis in the areas of card knowledge and skills development, advising on development of card acceptance infrastructure, new products, and developing partnerships with 'technology enablers,' as well as retailer education and best acceptance practice.
“We are establishing the new Nairobi office as a gateway through which MasterCard will liaise with its existing customers across the East African region. It will also be a launch pad for further expansion across the region, by providing advice to support MasterCard’s ongoing quest to shift consumers from traditional cash payments to non-cash payment systems, so that they can avoid the costs, risks and inefficiencies associated with cash,” comments Monehin.
Bringing the benefits of electronic payments to people across the African continent is a primary focus for MasterCard. “East Africa, and indeed Africa as a whole, has always been heavily reliant on cash – both in the consumer and corporate sectors,” says Charlton Goredema, Vice President and Market Manager for East Africa and Indian Ocean Islands for MasterCard Worldwide. “This dependence is costly – the costs of printing notes and keeping them secure are significant – and cash payments restrict an individual or company’s economic activity to their immediate geographic area.”
MasterCard has already been active in the Kenyan market working with banks and other business organisations to advise on developing payment solutions that are best suited for Kenyans. Most recently, in collaboration with Airtel & Standard Chartered Bank, the world's first virtual card that operates off a mobile wallet was launched in Kenya.
“PayOnline is a unique virtual card payment solution, developed specifically to address the needs of consumers in Kenya. At the Mobile World Congress 2011 this product was awarded top honours as the Best Mobile Money Product or Solution. PayOnline makes it possible for Kenyan Airtel clients to shop online, even if they do not have a bank account,” says Goredema. “This is just one way that MasterCard products are working to extend financial inclusion to all through the development of solutions that take into account the unique attributes of each local market.”
“MasterCard products make it simple and safe to process electronic payments anywhere in the world,” Goredema points out. “Consumers using electronic payment systems don’t have to worry whether the cash they are carrying is sufficient for their intended purchase, and they do not have to fear for their security, as is common when carrying a large amount of cash on their person.”
In addition, the electronic payments solutions brought to market by MasterCard facilitate transparency in banking, through innovation and security that provide clear transaction records at every step, allowing protection from fraudulent activities. Goredema believes that these solutions are key to the continued success of East Africa’s rapid economic growth.
“MasterCard’s products include debit, prepaid, mobile and credit card payment solutions, which can be used to avoid the pitfalls of cash,” says Goredema. “We have already used these products in a variety of revolutionary applications on the African continent, including prepaid solutions for transport, and the secure disbursement of citizens’ social security payments.”
MasterCard’s global payments expertise will be very relevant across East Africa and particularly in Kenya, as the country evolves to implement the National Payments Systems Bill, passed by the country’s government during 2011.
“We believe that the Bill is a recognition that efficient payment mechanisms are essential to the development of the Kenyan economy, and we look forward to working with policymakers to bring electronic payment solutions to this market,” says Goredema. “We have worked on similar projects across the globe, where we have responded to local needs with products that offer the best of MasterCard’s global experience.”
MasterCard will also be offering the services of MasterCard Advisors into the East African region, helping to ensure that best-practice principles are implemented across the payments network. MasterCard Advisors is the professional services arm of MasterCard that provides payments consulting, information, analytics, and customised services to financial institutions, governments and retailers worldwide.
“We have invested significant resources into understanding East Africa, its business dynamics, how its consumers operate and the unique conditions that make this region one of the most exciting places to do business,” says Goredema. “We realise that there is no one-size-fits-all strategy and each market has its own unique challenges, opportunities and needs. MasterCard has invested extensively in research both on the African continent, and globally, and we are equipped to offer advice on payment industry best practice at every level.
“For MasterCard, the opportunities Africa brings forth will push the payments frontier faster and further than ever before and we continue our vision to realise a world beyond cash, bringing greater efficiencies to the payments system,” concludes Goredema. “We look forward to now working even more closely with our customer financial institutions, businesses and consumers across East Africa to leverage new technologies and innovative payment methods to enable safe, simple and convenient ways for consumers to pay.”
About MasterCard
MasterCard (NYSE: MA) is a global payments and technology company. It operates the world’s fastest payments processing network, connecting consumers, financial institutions, merchants, governments and businesses in more than 210 countries and territories. MasterCard’s products and solutions make everyday commerce activities - such as shopping, traveling, running a business and managing finances - easier, more secure and more efficient for everyone. Learn more at mastercard.com or follow us on Twitter@mastercardnews or join the conversation on The Heart of Commerce Blog.

Disqus for ePayment News